The passport isn’t the problem.
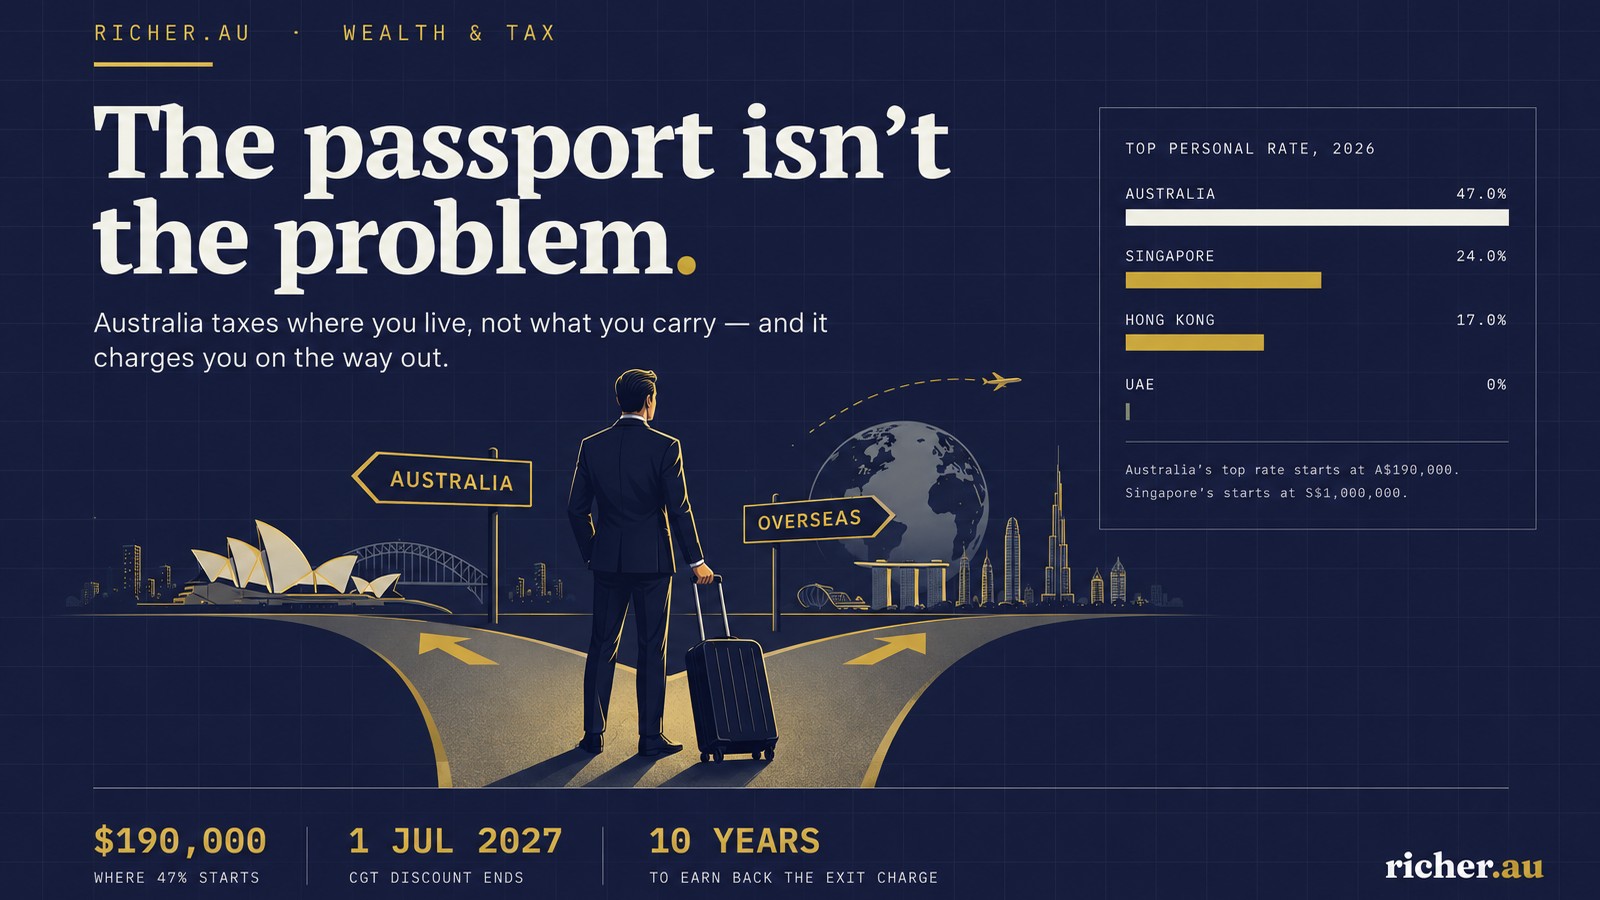
Australia taxes where you live, not which passport you hold — so the citizenship half of the question answers itself. The harder half is residence, and 2026 made it harder: a 47 per cent top rate, a new tax on large super balances, and the end of the 50 per cent CGT discount from July 2027. Here is what leaving actually costs, what it buys, and the one thing an exit charge makes impossible.
The short version
Australian citizenship costs nothing in tax. Australia taxes people who live here, and it does not care what passport they carry. The United States taxes its citizens wherever they are; Australia does not. So “should I stay a citizen?” is the wrong question, and answering it correctly saves a great deal of money.
The right question is whether to stay tax resident — and that question got materially more expensive in 2026. A 47 per cent top marginal rate now starts at $190,000. From 1 July 2026 a second layer of tax applies to superannuation balances above $3 million, and a third above $10 million. From 1 July 2027 the 50 per cent capital gains discount is gone, replaced by inflation indexation and a 30 per cent minimum tax. A minimum tax on discretionary trust distributions is drafted for 2028. Four measures, and between them they land squarely on the four things wealthy Australians actually earn from: capital gains, trusts, dividends and super.
And yet the arithmetic of leaving is worse than almost everyone assumes, for one reason that rarely makes it into the brochure. Australia charges a deemed disposal on the way out. Stop being a resident and the Tax Office treats you as having sold every asset that is not Australian real property, at market value, on that day. You cannot leave to escape a gain you already have. You can only leave to escape a gain you have not made yet. That single rule reorders the entire decision: it makes departure cheap for the young and the recently liquid, and ruinous for exactly the people most tempted by it.
What follows is the full arithmetic — what Australia charges, what the alternatives charge, what the exit costs, what you stop being able to claim once you go, and a break-even calculation you can run against your own numbers. Some of it argues for staying. Some of it does not. All of it is sourced, and every figure carries a date.
- What Australia actually charges, in 2026–27
- The four measures — and which of them are law
- Where the top one per cent actually earn their money
- What everyone else charges
- The regimes actually on offer
- What it costs to leave
- The charge on the way out
- Franking, the family home, and the costs no table shows
- What you give up that is not money
- Is anybody actually going?
- The break-even, worked
- Who should actually consider it
What Australia actually charges, in 2026–27
Start with the number everyone quotes. The top marginal rate is 45 cents in the dollar, and it begins at $190,000 of taxable income. Add the 2 per cent Medicare levy and the real top rate is 47 per cent. Add the Medicare levy surcharge, which a high earner without private hospital cover pays at 1.5 per cent above $164,000 for a single or $328,000 for a family, and it is 48.5 per cent.
The scale below that is more generous than it was. The bottom rate fell from 16 per cent to 15 per cent on 1 July 2026 and falls again to 14 per cent from July 2027, under legislation that received assent in March 2025. None of that reaches a household on $600,000. What reaches that household is the top bracket, and the top bracket has not moved since 2024 and is not indexed.
So a taxable income of $1,000,000 produces $415,870 of income tax and $20,000 of Medicare levy: $435,870, an average rate of 43.6 per cent. A taxable income of $600,000 produces $247,870, an average rate of 41.3 per cent. If that person also makes the full concessional superannuation contribution, Division 293 adds a further 15 per cent on the contribution — another $4,875, because their income exceeds the $250,000 threshold that has not moved since 2017–18.
Two things are worth saying plainly before the comparison starts. First, Australia’s headline rate is high but not extreme: Japan’s combined top rate is around 55.9 per cent, Portugal’s 53 per cent with the solidarity surcharge, South Korea’s 49.5 per cent, and the United Kingdom’s additional rate of 45 per cent begins at £125,140 — a much lower threshold in real terms than Australia’s. Second, Australia has no inheritance tax, no estate duty, no gift duty and no general wealth tax. Federal estate duty was abolished in 1979 and the last state death duties by 1982. For a family thinking about transferring capital between generations, that absence is worth more than several percentage points of income tax, and it is the single most under-weighted item on the entire scoreboard.
The four measures — and which of them are law
Most of the anxiety in 2026 is about a package announced on Budget night, 12 May 2026, and about one measure that predates it. It is worth separating what has actually been enacted from what has only been drafted, because the difference is about $50,000 a year to some households and nothing at all to others.
Division 296 is law. The Treasury Laws Amendment (Building a Stronger and Fairer Super System) Act 2026 received assent on 13 March 2026 and applies from 1 July 2026. Earnings attributable to the part of a total superannuation balance above $3 million attract an extra 15 per cent, on top of the fund’s 15 per cent — an effective 30 per cent. Above $10 million a further 10 per cent applies, taking it to 40 per cent. Both thresholds are indexed to CPI, and — importantly, because the original 2023 design did not do this — the tax as enacted applies to realised earnings, not to movements in the balance. The unrealised-gains version was dropped in the October 2025 redesign. The first assessments will be based on 30 June 2027 positions.
The capital gains change is law. The Treasury Laws Amendment (Tax Reform No. 1) Act 2026 received assent on 26 June 2026. From 1 July 2027 the 50 per cent CGT discount is replaced, for resident individuals, trusts and partnerships, by indexation of the cost base for inflation, plus a minimum effective tax rate of 30 per cent on the gain. It applies to broadly all CGT assets held at least twelve months — shares, bullion, business assets, property — not only real estate. Companies, superannuation funds and life insurers keep their existing treatment, and super funds keep the one-third discount.
The negative gearing quarantine is law. From the 2027–28 income year, net rental losses on established residential dwellings acquired after 7:30pm AEST on 12 May 2026 can only be offset against residential rental income or residential capital gains, or carried forward. They cannot reduce salary or business income. Interests acquired before that moment are grandfathered, and new residential dwellings are exempt. We have covered that measure, and the odds of it surviving the next election, in a separate piece.
The trust minimum tax is not law. A 30 per cent minimum tax on discretionary trust distributions, applied at the trustee level from 1 July 2028, was announced with the package. Exposure draft legislation appeared on 3 September 2026 and consultation closed on 18 September. The draft includes a three-year restructure rollover from 1 July 2027 and an “excluded election trust” escape for trusts willing to nominate beneficiaries in advance and stick to the nomination. The ATO’s own page says, in terms, that the measure is not yet law. Anyone restructuring a family trust today is restructuring against a draft.
Assets you hold on 30 June 2027 are treated as sold just before 1 July 2027 and reacquired at market value on that day — or under an apportionment method the Minister may prescribe. Nothing crystallises and no tax falls due on that date. The notional gain is deferred until you actually sell, and at that point the pre-July-2027 growth is taxed under the old rules, including the 50 per cent discount, while the post-July-2027 growth is taxed under the new ones. The practical consequence is administrative rather than financial: get a defensible valuation of every material asset as at 1 July 2027, whatever you decide about residence. Pre-CGT assets acquired before 20 September 1985 are also deemed sold and reacquired on that date, which ends their pre-CGT status for good.
Where the top one per cent actually earn their money
The four measures look scattergun until you look at how the money at the top is actually made. Analysis of ATO taxation statistics published in May 2026 found that for individuals with total income above $1 million, only 18 per cent of that income is salary and wages. Capital gains account for 26 per cent, partnership and trust distributions 24 per cent, and dividends 18 per cent. For the tier below — $250,000 to $1 million — the picture inverts: 57 per cent salary, 13 per cent trusts and partnerships, 8 per cent dividends, 6 per cent capital gains.
Read the package against that chart and it stops looking scattergun. Capital gains and trust distributions together are half the income of the top 1 per cent, and they are precisely what the CGT measure and the trust measure address. The top marginal rate, meanwhile, does most of its work on the tier below — the surgeons, partners and executives whose income is overwhelmingly salary, and who have almost no structural options at all.
At the very top of the Australian income distribution, wages are the smallest thing people earn. That is the whole design brief for the 2026 package — and the reason a top-rate comparison with Dubai tells you almost nothing useful.
richer.au, on ATO Taxation Statistics 2022–23What everyone else charges
Here is the comparison, for the jurisdictions Australians actually name when this conversation starts. Rates are top marginal rates on ordinary income as at the dates shown; every one of them hides detail, and the detail is usually where the money is.
| Jurisdiction | Top rate | Capital gains | Inheritance / estate | Wealth tax | Days to be resident |
|---|---|---|---|---|---|
| Australia | 47.0% | Indexation + 30% minimum from 1 Jul 2027 | None | None | 183, plus resides and domicile tests |
| Singapore | 24.0% | None | None (abolished 2008) | None | 183 in the preceding calendar year |
| United Arab Emirates | 0% | None | None | None | 183, or 90 with a residence permit and ties |
| Hong Kong | 17.0% | None | None (estate duty abolished) | None | Territorial — source, not residence |
| New Zealand | 39.0% | No general CGT; 2-year bright-line on property | None | None | 183 in any 12 months, or permanent abode |
| Switzerland (Zug – Geneva) | 21.9–43.2% | Exempt on private movable property | Cantonal; spouses exempt everywhere, most cantons exempt children | 0.13–0.86% of net assets | Ordinary Swiss residence rules |
| Monaco | 0% | None | Monaco-situs only; 0% to spouse and direct line | None | Residence permit; bank reference required |
| United Kingdom | 45.0% | 18% / 24% | 40% above £325,000, now residence-based | None | Statutory Residence Test |
| United States | 37% + 3.8% | 20% + 3.8% long-term | 40% above US$15m exclusion | None | Substantial presence — and citizenship |
| Italy | 43% + surcharges | 26% on financial assets | 4% to direct line above €1m per heir | IVIE 1.06% / IVAFE 0.2% on foreign assets | 183 days; flat-tax option for new residents |
| Portugal | 48% + 5% surcharge | 28% securities; property at marginal rates | None (10% stamp duty; family exempt) | AIMI 0.7–1.5% above €600,000 of property | 183 days |
| Cyprus | 35.0% | 0% on securities; 20% on Cyprus property | None | None | 183, or 60 with conditions |
| Malta | 35.0% | Remittance basis for non-doms | None | None | Programme-dependent |
| Japan | ~55.9% | 20.315% on listed shares | Up to 55% | None | 5 of the last 10 years for worldwide tax |
Three things stand out from that table, and none of them is the top rate.
The first is capital gains. Singapore, the UAE, Hong Kong and Monaco have no CGT at all. Switzerland exempts gains on private movable property — shares, in other words — across the whole country. New Zealand has no general CGT, although the Labour Party has announced a 28 per cent flat capital gains tax on property from 1 July 2027 and the New Zealand general election is on 7 November 2026, so that is a live risk rather than a settled feature. Against that, Australia is moving in the opposite direction: from 1 July 2027 a realised gain that would once have been taxed at an effective 23.5 per cent is taxed at something closer to a third.
The second is inheritance tax, and here Australia wins outright against most of the developed world. The United Kingdom charges 40 per cent above a nil-rate band frozen at £325,000 until 2031 — and since 6 April 2025 that charge follows residence rather than domicile, with a tail of up to ten years after you leave. The United States charges 40 per cent above a US$15 million exclusion. Japan charges up to 55 per cent. Australia charges nothing, and has charged nothing since 1982. For a family whose central financial objective is moving capital to the next generation intact, that is a far larger number than the difference between 47 and 24 per cent on one year’s income.
The third is wealth tax. Switzerland, the destination most often held up as the civilised alternative, levies an annual tax on worldwide net assets in every single canton, at rates between roughly 0.13 and 0.86 per cent. On $40 million of net assets that is between $52,000 and $344,000 a year, every year, whether or not anything was earned. Italy charges IVIE and IVAFE on foreign real estate and foreign financial assets. Portugal charges AIMI on property above €600,000. Australia charges none of these — though state land tax, with a 5 per cent foreign surcharge in New South Wales and a 4 per cent absentee surcharge in Victoria, is a wealth tax on one asset class in all but name, and it is the one that bites hardest on people who leave.
The capital gains change, worked
Take an asset bought on 1 July 2027 for $5 million and sold ten years later for $10 million, held by an individual on the top marginal rate. Inflation over the decade runs at 2.7 per cent a year, so the cost base indexes up by about 30 per cent, to $6.5 million.
- Under the old rules: a $5,000,000 nominal gain, halved by the 50 per cent discount to $2,500,000, taxed at 47 per cent — $1,175,000, or 23.5 per cent of the gain.
- Under the new rules: an indexed gain of $3,500,000, taxed at 47 per cent — $1,645,000, or 32.9 per cent of the gain. The 30 per cent minimum tax would have been $1,500,000, so on these numbers it does not bind; it binds when your marginal rate is lower, which is the entire point of it.
- In Singapore, the UAE, Hong Kong or Switzerland: nil.
That is a $470,000 difference on one transaction between the old Australian rules and the new ones, and a $1,645,000 difference between the new Australian rules and no capital gains tax at all. It is the largest single number in this article, and it is why the conversation is happening.
The regimes actually on offer
A top rate is a number on a page. What you can actually obtain is a different matter, and the market for wealthy residents has repriced sharply since 2023.
Singapore has a Global Investor Programme, and the numbers are serious: S$10 million into a new or expanded Singapore business, S$25 million into a designated fund, or a single family office with S$200 million under management deploying at least S$50 million locally. Renewal after five years requires the original conditions to still be met plus physical residence for more than half the period. The programme grants permanent residence, not citizenship; Singapore does not permit dual citizenship for adults; and male children who take up PR become liable for National Service. Foreigners buying residential property pay 60 per cent additional buyer’s stamp duty — 65 per cent through an entity or trust — which on a S$8 million house is S$4.8 million of duty on day one.
The UAE is the genuine zero. No personal income tax, no capital gains tax, no inheritance tax, and the Ministry of Finance has repeatedly said no personal income tax is planned. The Golden Visa gives a renewable five or ten-year residence permit. What it does not give, and cannot give, is citizenship: Emirati nationality cannot be applied for at all. It is granted only by nomination from the Rulers’ Courts or the Cabinet. A wealthy Australian family in Dubai is a permanent guest, and so are their children, who acquire no local status by being born or raised there.
Hong Kong reopened its Capital Investment Entrant Scheme in March 2024 at HK$30 million, and by its two-year milestone had approved 1,762 applicants against some HK$95 billion of expected investment. The tax case is strong: a 15 per cent standard-rate cap on the first HK$5 million of income, no CGT, no estate duty, and buyer’s stamp duty for non-permanent residents cut to zero in February 2024. The non-tax case is the problem, and we come to it below.
The United Kingdom abolished the non-domicile regime on 5 April 2025 and replaced it with a four-year exemption for foreign income and gains, available only to people who have not been UK resident for the previous ten consecutive years. Claiming it costs you the personal allowance and the CGT annual exempt amount. After four years you are taxed on worldwide income at 45 per cent, and after ten years of residence in the previous twenty you are inside the inheritance tax net on worldwide assets, with a tail of up to ten years after you leave. For an Australian, the UK is now a worse tax destination than Australia on almost every measure that matters.
Italy charges a flat €300,000 a year — raised from €200,000 on 1 January 2026, which was itself raised from €100,000 in August 2024 — on all foreign income, for up to fifteen years, plus €50,000 per family member. People who moved before each increase keep the rate in force when they arrived. At €300,000 the regime pays for itself above roughly €700,000 of foreign income and becomes very attractive above €3 million. Greece offers the same structure at €100,000, plus a €500,000 Greek investment requirement. Switzerland’s lump-sum regime sets deemed income at seven times the rent or rental value of the Swiss home, with a federal minimum of CHF 434,700; KPMG says the resulting bill can be under CHF 100,000, but five cantons including Zurich and both Basels have abolished it.
Meanwhile the European door is closing. Spain abolished its golden visa in April 2025. Portugal removed the property route in 2023 and, in May 2026, extended naturalisation from five years to seven for EU and Portuguese-speaking nationals and ten for everyone else, with no transitional protection for residency already accrued. Greece doubled and tripled its thresholds in September 2024. The European Court of Justice struck down Malta’s citizenship-by-investment scheme in April 2025. The programmes that are growing — the UAE, Hong Kong, New Zealand, the new US “Gold Card” — are all outside the European Union.
Australia closed the Business Innovation and Investment Program — including the Significant Investor stream — to new applications on 31 July 2024. Its replacement, the National Innovation visa (subclass 858), has no investment threshold of any kind; it is a talent and achievement visa. Australia has simply stopped competing for purchased residency, at the same time as the UAE and Singapore have made it the centre of their strategy. Whatever you think of that decision, it means the inbound and outbound flows are no longer symmetrical, and comparisons that treat them as if they were are wrong.
What it costs to leave
Now the part that the rate tables never show. Ceasing Australian tax residency is not a switch you flip. It is a transaction, and it is priced.
The charge on the way out
When you stop being an Australian resident for tax purposes, CGT event I1 happens. You are treated as having disposed of every CGT asset you own, at market value, on that day — with one exception: taxable Australian property, which means Australian real estate, indirect interests in it, and the assets of an Australian permanent establishment. Everything else is caught. Listed shares. Unlisted shares in your own private company. Foreign property. Crypto. Managed funds. Artwork.
Take a household leaving with a $6 million portfolio carrying $3 million of unrealised gain, all held more than twelve months, on the top marginal rate. The exit charge is $3,000,000 halved to $1,500,000 and taxed at 47 per cent: $705,000, assessable in the year of departure, payable in cash, on assets nobody has sold.
There is an alternative. Section 104-165 lets an individual elect to disregard the whole event. But the price of that election is that the assets are deemed to be taxable Australian property until either a CGT event happens to them or you resume Australian residency — which means every dollar of growth from that day forward stays inside the Australian CGT net, no matter where you live or where the asset is. For thirty years that election has been the standard deferral play. From 1 July 2027 it becomes considerably worse, because an individual who is a foreign resident for even a single day of the ownership period loses indexation entirely. You would be electing to keep an Australian tax exposure while forfeiting the relief that makes the new Australian regime tolerable.
You cannot leave Australia to escape a gain you already have. The exit charge takes it on the way out. You can only leave to escape a gain you have not made yet — which means the manoeuvre works for the young and the recently liquid, and is ruinous for exactly the people most tempted by it.
richer.auThis is the structural fact that reorders the whole decision. The founder who sells a business for $60 million and then moves to Dubai has saved nothing, because the gain was crystallised while resident. The founder who moves to Dubai first and sells later has not escaped either, because the private company shares are not taxable Australian property and so CGT event I1 taxes them at market value on the day of departure — which, if the business is already worth $60 million, is the same bill. The only version that works is moving before the value exists, and that is a decision made in your thirties about a business you have not built yet, not in your fifties about one you have.
The recurring costs the tables do not show
Beyond the exit charge, four ongoing losses apply to a non-resident, and together they usually exceed the annual tax saving for anyone whose wealth is in Australian assets.
Franking credits stop being refundable. This is the big one for Australian retirees and it is almost never mentioned. A non-resident receiving fully franked Australian dividends pays no further Australian tax — the dividend is exempt from withholding. But excess franking credits are refundable only to residents. Consider a household drawing $400,000 a year of fully franked dividends. Those dividends carry $171,429 of franking credits. A resident whose income sits in pension-phase superannuation or a low-rate structure gets some or all of that back in cash. A non-resident gets none of it, ever. That is a $171,429 annual cost of leaving, invisible on every comparison table in this article, and it is charged against precisely the income stream that wealthy retired Australians live on.
The main residence exemption disappears. Since 1 July 2020 a foreign resident cannot claim the main residence exemption at all, unless they satisfy a narrow life-events test requiring the foreign residency to have run six years or less and to coincide with terminal illness, the death of a spouse or minor child, or a relationship breakdown. It is not apportioned. Live in a house for thirty years as a resident, move overseas, sell it one day later, and the entire gain is taxable. On a family home bought for $1.2 million and worth $4 million, that is a $2.8 million gain that was worth nothing to the Tax Office the day before you left. The rule is brutal, and the practical response is simple: if you are going, sell the house before you go, or keep it until you come back.
Your SMSF may have to be wound up. A self-managed fund must be established in Australia or hold assets here, have its central management and control ordinarily in Australia, and satisfy the active member test. There is a safe harbour of up to two years for central management and control being temporarily overseas. Beyond that, the ATO’s own advice is unambiguous: roll the money into an APRA-regulated fund and wind the SMSF up, or it becomes non-complying. For a family whose structure is built around an SMSF holding a commercial property, that is not an inconvenience — it is the dismantling of the structure.
Your superannuation is locked and stays Australian. The departing Australia superannuation payment exists, but it explicitly excludes Australian citizens, New Zealand citizens and Australian permanent residents. A forty-five-year-old who moves to Dubai cannot touch their super. It sits in an Australian fund, taxed under Australian rules at 15 per cent on earnings, for fifteen years or more, in a country that gives it no recognition and no concession whatsoever. And since 1 July 2026 the Division 296 thresholds attach to total superannuation balance — whether and how they reach a non-resident’s balance is exactly the kind of question to resolve with advice before you go, not after.
| What changes when you cease residency | Before | After |
|---|---|---|
| All non-property CGT assets | Taxed on realisation | Deemed sold at market value on departure (CGT event I1) |
| Excess franking credits | Refundable in cash | Lost entirely |
| Main residence exemption | Full exemption | Unavailable, not apportioned |
| CGT discount on Australian property | 50% | Apportioned for the resident part of ownership since 8 May 2012 |
| Sale of any Australian property | Clearance certificate | 15% withheld at settlement from the first dollar |
| Income tax scale | Tax-free threshold, then 15% | 30% from the first dollar; no Medicare levy |
| Land tax, NSW | Threshold $1,075,000 | 5% surcharge with no threshold at all |
| Land tax, Victoria | General scale | 4% absentee owner surcharge |
| Superannuation access | At preservation age | Unchanged — no early release for citizens or PRs |
| Self-managed fund | Complying | 2-year safe harbour, then roll over and wind up |
| Medicare | Enrolled | Eligibility turns on residing in Australia |
| HELP / HECS debt | Repaid through the tax system | Still payable; annual worldwide income reporting to the ATO |
| Australian citizenship | Held | Unaffected — no residence-abroad ground for loss |
| Permanent residency | Held | Travel facility expires; Resident Return Visa needs 2 years in 5 |
The one asymmetry that decides it: citizen or permanent resident
Here is where the two halves of the original question genuinely diverge.
An Australian citizen can leave completely. Citizenship carries no tax consequence at all — Australia taxes residence, not nationality, and the Australian Citizenship Act 2007 contains no ground on which citizenship is lost by living abroad. The automatic-loss provision for acquiring another nationality was repealed in 2002. A citizen can move to Dubai for twenty years, pay nothing to Australia on foreign income, and walk back in through the arrivals hall on a whim. The only real maintenance cost is the electoral roll: overseas elector registration lasts six years from departure, then annual extensions that must be requested in the three months before expiry, and if you miss that window the cancellation is expressly not reviewable.
A permanent resident cannot. The permanent visa does not lapse, but its travel facility does — usually five years from grant. After that, re-entry requires a Resident Return Visa. The subclass 155 gives five years if you have been lawfully in Australia for two years out of the last five; short of that you are arguing “substantial ties of benefit to Australia” for a one-year grant, or falling back on the subclass 157, which gives three months. The fee rose from $490 to $1,475 on 1 July 2026, an increase of more than 200 per cent.
Look at what that does. Two years in five is an average of 146 days a year in Australia. The 183-day tax residency test is 183 days. A permanent resident trying to preserve re-entry rights is spending close to the line at which Australian tax residency starts arguing back — and the resides and domicile tests do not care about day counts at all. It is an uncomfortable place to stand. A citizen has no such tension, which is the plain, practical reason long-term residents who are seriously contemplating a move naturalise first and leave second. The passport is the cheapest option in the entire decision.
A child born overseas to an Australian citizen can become a citizen by descent. But a parent who is themselves a citizen by descent must have lived lawfully in Australia for at least two years before they can pass citizenship to their own overseas-born children. So the family that leaves passes citizenship to its children, and those children pass nothing to their children unless they come back and live here for two years. In the UAE, where citizenship cannot be applied for and is granted only by nomination, there is no local status to replace it with. Two generations abroad and the Australian connection ends by operation of a rule almost nobody reads before they go.
What you give up that is not money
It is easy to write this section badly — either as a patriotic list of beaches, or as a shrug. The honest version is a scoreboard with real losses on it.
Liveability. The Economist Intelligence Unit’s 2026 Global Liveability Index, published on 7 July 2026 and covering 173 cities, put Melbourne third and Sydney fourth or fifth — sources differ on that one place — with Adelaide eighth. Three Australian cities in the global top eight. Singapore was 26th, Hong Kong 44th, London 54th. Mercer’s most recent Quality of Living ranking, from December 2024, put Sydney 12th, Singapore 30th, Dubai 83rd and Abu Dhabi 85th.
Human development. Australia ranks 7th on the UN Human Development Index with a gross national income per head of US$58,277. Singapore ranks 13th on US$111,239. Australia converts roughly half the income into six places more human development. Life expectancy here is 83.9 years; in the United States it is 79.3.
Healthcare. The Commonwealth Fund’s Mirror Mirror 2024 study ranked Australia’s health system first of ten high-income countries, first on equity, and among the best on outcomes; its noted weakness is access and affordability, and GP bulk-billing has slipped from a 2020–21 peak of 89 per cent to 79 per cent in 2025. Even so, compare the alternative. An expatriate in Singapore on an employment pass is not covered by MediShield Life at all; international private medical insurance runs S$3,600 to S$9,600 or more per person per year, and Singapore’s medical cost inflation is projected at 14 per cent for 2026. In Dubai, comprehensive individual cover runs AED 6,000–14,000 for someone aged 18 to 40 and AED 15,000–30,000 or more from 61. Australian private health premiums rose 4.41 per cent on 1 April 2026, on top of a universal system you do not have to buy. The wealthy expatriate is not buying better healthcare. They are buying the same healthcare, personally, forever, with pre-existing conditions priced in from whatever age they left.
Schooling. Almost a wash, and worth saying so. Elite independent schools in Sydney and Melbourne charge A$42,000–55,000 a year in the senior years. Premium international schools in Singapore charge S$55,000–57,000 before registration, building levies, buses and exam fees, which add 10–18 per cent; two children at that level runs S$95,000–140,000 all in. Dubai’s top tier runs AED 95,000–120,000 at secondary. The difference is that Australia also has a free, high-performing public alternative, and the expatriate destinations do not.
Air. Australia recorded a national PM2.5 of 4.4 micrograms per cubic metre in 2025 and is one of only thirteen countries and territories on earth that met the World Health Organization’s annual guideline of 5. The UAE recorded 36.4 — the thirteenth most polluted country in the world, at more than eight times Australia’s level and seven times the guideline. Singapore recorded 11.9, Hong Kong 15.7. For a family with young children or anyone with respiratory sensitivity, that is not a lifestyle preference. It is a health outcome.
Property. On Knight Frank’s prime residential index for 2025, US$1 million buys 42 square metres in Sydney, 34 in New York, 33 in London, 28 in Singapore and Geneva, 23 in Hong Kong and 16 in Monaco. Only Dubai, at 62 square metres, is materially cheaper — and Dubai prime prices rose 25.1 per cent in 2025, which took sixteen square metres off that number in a single year. Measured against local earnings, Numbeo’s price-to-income ratios say the same thing from the other side: Perth 6.6, Melbourne 7.6, Brisbane 8.0, Sydney 12.5, against Singapore 24.9 and Hong Kong 35.2.
And the honest counter-column. Three things genuinely go the other way. Personal safety perception: Numbeo’s crowd-sourced 2026 safety index puts Dubai at 83.8, Hong Kong 78.2 and Singapore 77.7, against Sydney 66.2, Brisbane 61.8, Perth 57.8 and Melbourne 55.7. The OECD’s Better Life Index shows Australia below the OECD average on feeling safe walking alone at night and on long working hours — two of only eleven dimensions, but two real ones. Governance: Transparency International’s 2025 index scores Singapore 84 and Australia 76, and that gap is earned. And, obviously, the tax.
Smartraveller advises Australians to exercise a high degree of caution in Hong Kong. Its assessment says security laws “may be interpreted broadly” and can apply to activities conducted outside Hong Kong, including social media posts; that people “have been imprisoned for acts considered seditious, including wearing clothing with a political slogan”; that you could be detained without charge for up to sixteen days and denied access to a lawyer for forty-eight hours; and that Hong Kong authorities have issued arrest warrants and financial rewards targeting individuals living outside Hong Kong, including in Australia. Reporters Without Borders ranks Hong Kong 140th of 180 on press freedom in 2026, and Singapore 123rd. None of that is a reason nobody should move. It is a reason to price the risk rather than ignore it.
Is anybody actually going?
This is where the genre usually cites a millionaire migration report. It is worth knowing what happened to that report.
For a decade the “millionaire exodus” story rested almost entirely on the Henley & Partners Private Wealth Migration Report and the underlying data from a firm called New World Wealth. In July 2025 Tax Policy Associates published a forensic analysis of that dataset. It found that the definition of wealth had changed three times between 2023 and 2025 — from all property, to debt-free property, to no real estate at all — while the published figures barely moved, which is statistically very hard to explain. It found last-digit distributions in the published numbers that would occur naturally about once in 240,000 times. It found UK millionaire counts roughly double the ONS and HMRC figures. And it found that New World Wealth has one employee, claiming to track the holdings, cash, crypto and debt of 150,000 individuals partly via LinkedIn.
In June 2026 Henley published the next edition without any migration numbers at all, replacing them with a 0–100 “wealth mobility competitiveness” score. Its own explanation is that the report “expands the analytical focus from migration outcomes to the structural drivers that shape wealth mobility over time.” The last edition to carry figures, in 2025, projected a net inflow to Australia of 1,000 millionaires — an inflow, not an outflow — against 9,800 to the UAE and an outflow of 16,500 from the United Kingdom.
What does Australia’s own data say? The ABS recorded 23,340 long-term resident departures in July 2026, up 6.6 per cent on July 2025, against 9,730 permanent arrivals. But the ABS itself warns, in terms, that these statistics “report on the number of international border crossings rather than the number of people” and “should not be used as a measure of overseas migration.” More to the point, the ABS does not disaggregate departures by wealth, income or occupation. There is no Australian official source that counts departing millionaires. Meanwhile Australia recorded record net permanent and long-term arrivals in 2025, and net long-term arrivals rose further into 2026.
The evidentiary base for a wealthy Australian exodus consists of one dataset whose publisher stopped publishing it after a statistical audit, amplified by firms that sell relocation services. That is not a reason to dismiss the question. It is a reason to answer it with your own arithmetic rather than somebody else’s headline.
richer.auThe break-even, worked
Everything above is context. This is the calculation. The numbers are richer.au’s own, built from the verified rates in this article, and you should run the same structure against your own position rather than adopting ours.
Take a household with $12 million of investment assets, $3 million of unrealised gain sitting inside the non-property portion, and $700,000 a year of Australian investment income. Of that income, $400,000 arrives as fully franked dividends carrying $171,429 of franking credits; the rest is interest and distributions.
Staying
Taxable income of $700,000 produces $280,870 of income tax plus $14,000 of Medicare levy — $294,870. The $171,429 of franking credits is applied against that, leaving $123,441 actually payable. Measured against the $528,571 of cash the household actually receives, that is an effective rate of 23.4 per cent. Not 47.
Leaving
As a non-resident, fully franked dividends are exempt from Australian withholding tax, so the $400,000 arrives clean. The franking credits are lost, but there was no tax to apply them against. Interest attracts 10 per cent withholding — about $12,857. In the UAE nothing further is payable. Australian tax bill: roughly $12,857.
So the gross annual saving is about $110,584. That is a real number and a large one. It is also less than a third of what a naive 47-versus-nil comparison would predict, and the reason is franking. Australia’s dividend imputation system is the single most valuable feature of the Australian tax code for a wealthy Australian investor, and it is the feature that a move abroad destroys most completely.
Now the costs
Against that saving, set the recurring costs of being elsewhere: comprehensive family medical cover bought privately for life, international schooling premiums where they apply, travel home, and the cross-border tax and structuring advice that becomes permanent rather than occasional. For a family of four in their late forties, net of the Australian costs no longer incurred, $40,000 a year is a conservative figure. That leaves a net annual benefit of roughly $70,000.
And then the entry ticket. CGT event I1 on $3 million of unrealised gain, at the top marginal rate with the 50 per cent discount, is $705,000, payable in the year of departure.
$705,000 divided by $70,000 is a payback period of just over ten years — ten years in which you must be genuinely, defensibly non-resident the entire time, in which you cannot sell the family home without losing its exemption, in which your superannuation sits untouchable, and at the end of which you have broken even.
Now run the same household with only $500,000 of embedded gain — someone who has recently sold, or who is young enough not to have accumulated one. The exit charge is $117,500. The payback is twenty months.
Who should actually consider it
Taking all of it together, here is where the arithmetic genuinely lands.
It does not work for the person who most wants it to. Someone in their fifties or sixties, with a large embedded gain, an Australian share portfolio producing franked income, a family home they intend to sell, and an SMSF, is the worst possible candidate. They pay the largest exit charge, lose the most valuable feature of the Australian system, forfeit the main residence exemption, have to dismantle their fund, and cannot access the super they are leaving behind. The apparent 47-per-cent motivation is, in their actual circumstances, closer to 23 per cent after franking.
It works for the founder who moves before the value exists. If the asset has not been built yet, there is nothing for CGT event I1 to bite on. This is a decision made early, about a company that does not yet have a valuation, not late, about one that does. Everything else is a rearguard action against a charge that has already attached.
It works for the genuinely mobile professional with no Australian asset base. Salary income, no embedded gains, no Australian property, no franked dividends. Here the comparison really is 47 per cent against nil, the exit charge is trivial, and the saving starts on day one. That person should also understand what they are buying: a permanent, personally funded healthcare position, and a residence permit rather than a citizenship.
It works — partially and specifically — for the very large single liquidation. But not the way people think. The gain must accrue while you are already non-resident. Selling as a resident, or leaving with the asset and triggering I1, produces the same bill. The only lawful version requires the residence change to precede the value, not the sale, and it requires the change to be genuine: the resides and domicile tests do not count days, they look at where your life is.
And for almost everyone else, the answer is to stay and structure properly. Make the 1 July 2027 valuations. Understand which of your gains sit under the old rules and which under the new. Use the new-build CGT election where it applies. Watch the trust draft. Keep the passport, because the passport costs nothing.
1. Obtain and document a defensible market valuation of every material CGT asset as at 1 July 2027 — the choice between market value and the prescribed apportionment method does not have to be made until you actually sell, but the evidence has to exist now. 2. Identify which assets you are likely to realise before that date and model both treatments. 3. Confirm whether any of your residential holdings qualify as new residential dwellings, because the 50 per cent discount election survives for them. 4. Review every family trust against the September 2026 exposure draft and the three-year restructure rollover that runs from 1 July 2027 to 30 June 2030. 5. If you hold pre-CGT assets from before 20 September 1985, understand that their pre-CGT status ends on 1 July 2027 and get them valued first.
The people who end up Richer through a change in the rules are rarely the ones who move countries. They are the ones who worked out, before anyone moved anything, exactly what the move was buying — and then found that the honest number was a third of the advertised one.
Frequently asked questions
Does Australian citizenship itself cost me anything in tax if I live overseas?
No. Australia taxes residence, not nationality. An Australian citizen who ceases to be an Australian tax resident is taxed only on Australian-sourced income and on taxable Australian property, exactly like any other foreign resident. This is the opposite of the United States, which is one of only two countries in the world that taxes its citizens on worldwide income wherever they live, and which charges an expatriation tax on renouncing. Australia has no citizenship-based filing obligation and no exit tax on giving up the passport. Its equivalent charge, CGT event I1, attaches to ceasing residency, not to nationality.
What is CGT event I1, and is there any way around it?
When you stop being an Australian tax resident you are treated as having sold, at market value, every CGT asset you own other than taxable Australian property — which is broadly Australian real estate and indirect interests in it. Shares, private company shares, foreign property and crypto are all caught. You can elect under section 104-165 to disregard the event, but the assets are then deemed to be taxable Australian property until you sell them or return, so all future growth stays inside the Australian CGT net. From 1 July 2027 that election looks considerably worse, because an individual who is a foreign resident for even a single day of the ownership period gets no cost-base indexation at all.
Is the 50 per cent capital gains discount really gone?
For resident individuals, trusts and partnerships, yes — from 1 July 2027, under the Treasury Laws Amendment (Tax Reform No. 1) Act 2026, which received assent on 26 June 2026. It is replaced by indexation of the cost base for inflation plus a minimum effective tax rate of 30 per cent. Companies and superannuation funds are unaffected, and super funds keep the one-third discount. Investors in new residential dwellings and affordable housing can elect to keep the 50 per cent discount (up to 60 per cent for affordable housing) instead. Assets held on 30 June 2027 are deemed sold and reacquired at market value on 1 July 2027, but nothing crystallises and no tax falls due on that date.
Do I still get franking credit refunds if I move overseas?
No, and this is the most expensive detail in the whole decision for anyone living on Australian dividends. Fully franked dividends paid to a non-resident are exempt from Australian withholding tax, so no further tax is payable — but refundability of excess franking credits requires you to be an Australian resident for the full income year. The credits are simply lost. A household drawing $400,000 of fully franked dividends carries about $171,429 of credits; as a resident in a low-rate structure much of that comes back in cash, and as a non-resident none of it does.
Can I sell my Australian family home after I move overseas?
You can, but the main residence exemption will almost certainly not apply. Since 1 July 2020 foreign residents cannot claim it at all unless they satisfy a narrow life-events test — foreign residency of six years or less, combined with terminal illness, the death of a spouse or minor child, or a relationship breakdown settlement. The exemption is lost entirely rather than apportioned, and residency at the time of the CGT event is what counts. Separately, since 1 January 2025 the foreign resident capital gains withholding rate is 15 per cent, applied from the first dollar with no property-value threshold, so 15 per cent of the sale price is withheld at settlement unless a variation is obtained.
Can I take my superannuation with me?
No. The departing Australia superannuation payment is available to temporary residents only; the ATO’s eligibility rules expressly exclude Australian citizens, New Zealand citizens and Australian permanent residents. Your balance stays in the Australian system, preserved until you meet a normal condition of release, with earnings taxed at 15 per cent in the accumulation phase. New Zealand citizens leaving permanently can transfer under trans-Tasman portability; nobody else can. If you run an SMSF, the additional problem is residency of the fund itself: central management and control has a safe harbour of up to two years overseas, after which the ATO’s advice is to roll the money to an APRA-regulated fund and wind the SMSF up.
Will I lose my permanent residency if I leave Australia?
The visa itself does not lapse, but its travel facility does, usually five years after grant. Re-entry then requires a Resident Return Visa. The subclass 155 gives up to five years if you have been lawfully in Australia for two years out of the last five; otherwise you are arguing substantial ties for a shorter grant, or relying on the subclass 157, which is valid for three months. The application charge rose from $490 to $1,475 on 1 July 2026. Two years in five is an average of 146 days a year in Australia, which sits uncomfortably close to the tax residency tests — a tension citizens do not have.
Which country actually has the lowest tax for a wealthy Australian?
On headline arithmetic, the United Arab Emirates: no personal income tax, no capital gains tax, no inheritance tax, and no announced plans to introduce any. Monaco is comparable but far more expensive to live in and harder to enter. Singapore and Hong Kong charge tax on income but nothing on capital gains or estates. Switzerland exempts gains on private shares but levies an annual wealth tax in every canton. The right comparison is never the headline rate, though — it is your own effective rate after franking, against the destination’s rate plus the cost of privately buying everything Australia currently provides.
Are wealthy Australians actually leaving in large numbers?
There is no reliable evidence that they are. The dataset that produced a decade of “millionaire exodus” headlines stopped publishing migration figures in its June 2026 edition, after a 2025 statistical analysis found digit distributions that would occur naturally about once in 240,000 times and counts that contradicted official UK statistics by roughly 100 per cent. Its last edition with figures projected a net inflow of 1,000 millionaires to Australia. The ABS records rising long-term resident departures but expressly warns that its border-crossing data cannot be used as a migration measure, and it does not disaggregate by wealth at all. Australia recorded record net permanent and long-term arrivals in 2025.
Sources
Every figure below was checked against its primary source on 13 September 2026. Where a rate or threshold has since been updated, the date of access is the date that applies.
- ATO, Tax rates – Australian residents, 2026–27 scale. Accessed 13 Sep 2026.
- ATO, Tax rates – foreign residents, 2025–26 scale.
- ATO, Medicare levy surcharge income thresholds and rates, 2026–27.
- Treasury Laws Amendment (More Cost of Living Relief) Act 2025, No. 28, 2025, assent 27 Mar 2025 — legislation.gov.au.
- ATO, Division 293 tax — $250,000 threshold, 15 per cent.
- Treasury Laws Amendment (Building a Stronger and Fairer Super System) Act 2026, No. 8, 2026, assent 13 Mar 2026 — legislation.gov.au.
- ATO, Better targeted superannuation concessions — Division 296, thresholds, CPI indexation, start date.
- Treasury Laws Amendment (Tax Reform No. 1) Act 2026, No. 49, 2026, assent 26 Jun 2026 — legislation.gov.au.
- Australian Government, Budget 2026–27: Tax reform.
- ATO, Tax reform: negative gearing and capital gains tax.
- PwC Australia, CGT and housing tax reform, 2026 — mechanics, exclusions, effective rates above 47 per cent.
- BDO Australia, Changes to the capital gains tax discount, 2026.
- ATO, Minimum tax on discretionary trusts — “this measure is not yet law”.
- Treasury, exposure draft on discretionary trusts, released 3 Sep 2026, consultation closed 18 Sep 2026.
- ATO, Contributions caps, 2026–27 — $32,500 concessional, $130,000 non-concessional.
- ATO, Transfer balance cap — $2.1m from 1 Jul 2026.
- ATO, Refund of franking credits, 2026 instructions.
- ATO, Withholding from dividends paid to foreign residents — franked dividends exempt.
- ATO, Withholding rates — interest 10 per cent, unfranked dividends and royalties 30 per cent.
- ATO, How changing residency affects CGT — CGT event I1 and the section 104-165 election.
- ATO, Main residence exemption for foreign residents — removed from 1 Jul 2020, life-events test.
- ATO, Foreign resident capital gains withholding — 15 per cent, no threshold, from 1 Jan 2025.
- ATO, Your tax residency — the four statutory tests.
- ATO, Departing Australia superannuation payment — citizens and permanent residents excluded.
- ATO, Check your fund is an Australian super fund — three residency tests, two-year safe harbour.
- ATO, Study and training loan overseas repayments — worldwide income reporting.
- ATO, Paying superannuation death benefits; ATO Schedule 12 — 17 and 32 per cent including Medicare levy.
- ATO, Taxation Statistics 2023–24, released 17 Jun 2026; Snapshot. The ATO does not publish a top-1 per cent share of net tax; the bracket counts used here are from the published tables.
- ABC News, analysis of ATO Taxation Statistics 2022–23 table 10, 10 May 2026 — income composition by band.
- Revenue NSW, Surcharge land tax — 5 per cent, no threshold.
- State Revenue Office Victoria, absentee owner surcharge — 4 per cent from the 2024 land tax year.
- Department of Home Affairs, Resident Return Visa (subclasses 155 and 157); fee increase to $1,475 from 1 Jul 2026 as reported by ABC News, 2 Jul 2026.
- Department of Home Affairs, BIIP closure and refunds — closed to new applications 31 Jul 2024; National Innovation visa (subclass 858).
- Australian Citizenship Act 2007 — cessation provisions; section 16 two-year residence condition on citizenship by descent.
- Australian Electoral Commission, Overseas electors.
- PwC Worldwide Tax Summaries, country pages for Singapore, UAE, Hong Kong, New Zealand, Switzerland, Italy, Portugal, Cyprus, Malta, Japan and the United States, reviewed Jun–Sep 2026.
- KPMG Switzerland, Lump-sum taxation; Swiss Federal Department of Finance, Lump-sum taxation; KPMG, Clarity on Swiss Taxes, May 2026.
- Singapore EDB, Global Investor Programme factsheet, updated 21 Feb 2025.
- Government of the UAE, Golden visa, updated 28 Jul 2026; UAE Ministry of Finance, domestic minimum top-up tax.
- New CIES Hong Kong, investment requirement; Hong Kong Government, two-year milestone press release, 2 Mar 2026.
- HM Treasury, Reforming the taxation of non-UK domiciled individuals; House of Commons Library CBP-10618, 7 Apr 2026.
- Italy: 2026 Budget Law, approved 30 Dec 2025, raising the Article 24-bis flat tax to €300,000 — PwC Italy, 23 Jul 2026.
- Portugal: Lei Orgânica n.º 1/2026, in force 19 May 2026 — naturalisation extended to seven and ten years.
- Court of Justice of the European Union, Case C-181/23 Commission v Malta, judgment 29 Apr 2025.
- Economist Intelligence Unit, Global Liveability Index 2026, published 7 Jul 2026.
- Mercer, Quality of Living City Ranking, 3 Dec 2024 — the most recent edition.
- UNDP, Human Development Report 2025, statistical annex.
- Commonwealth Fund, Mirror Mirror 2024 — Australia first of ten.
- AIHW, bulk-billing and out-of-pocket costs; industry-wide private health premium increase of 4.41 per cent effective 1 Apr 2026.
- IQAir, World Air Quality Report 2025.
- Knight Frank, Prime International Residential Index, The Wealth Report 2026.
- Numbeo, Quality of Life, Cost of Living and Crime indices, 2026 mid-year. Crowd-sourced perception data.
- Transparency International, Corruption Perceptions Index 2025; World Justice Project, Rule of Law Index 2025; Reporters Without Borders, 2026 Index.
- DFAT Smartraveller, Hong Kong travel advice.
- Tax Policy Associates, analysis of the Henley & Partners millionaire migration data, 27 Jul 2025; Henley & Partners, Private Wealth Migration Report 2026 methodology, 19 Jun 2026; 2025 press release for the last published figures.
- UBS, Global Wealth Report 2026, 30 Jun 2026.
- ABS, Overseas Arrivals and Departures, July 2026, released 11 Sep 2026, with the ABS’s own caveat that the series is not a measure of migration.
- Cotality Home Value Index, 31 Aug 2026 — national median dwelling value $912,885.
Keep reading
James Zhang is an Australian investor and company director, with interests spanning residential and commercial property, shares, ETFs, commodities and private businesses. More about James.
About these figures. Every rate, threshold and statistic in this article carries the date at which it was verified, and all of them were checked on 13 September 2026. The break-even model, the worked capital gains example and the effective-rate calculations are richer.au’s own and are clearly labelled as such; they are illustrations built on published rates, not forecasts, and they take no account of any individual’s circumstances. Tax residency is determined by facts, not by intention or by day counts alone, and ceasing Australian residency has consequences that cannot be reversed by returning. Nothing here is personal tax, migration, legal or financial advice.
Get richer, one decision at a time
New articles as they land.
Property, shares, commodities and tax strategy — worked examples with real Australian figures and no product spruiking. One email when something new goes live.
No spam · unsubscribe any time